Towngas stock forecast 2027–2029
MyStockButler's October 2026 analysis: Towngas's weighted value is HK$6.28 in October 2027, an 8% loss including dividends. Towngas's forecast hinges on modest mainland growth, a RMB0.55/m³ margin and stable Hong Kong utility earnings.
Where could Towngas's shares be in each forecast year?
Weighted value is HK$6.28 in October 2027. That is an 8% loss including dividends. Weighted value is HK$5.45 in October 2029, an 11% loss. The bear case has 28% probability. The base case has 55%, and the bull case 17%.
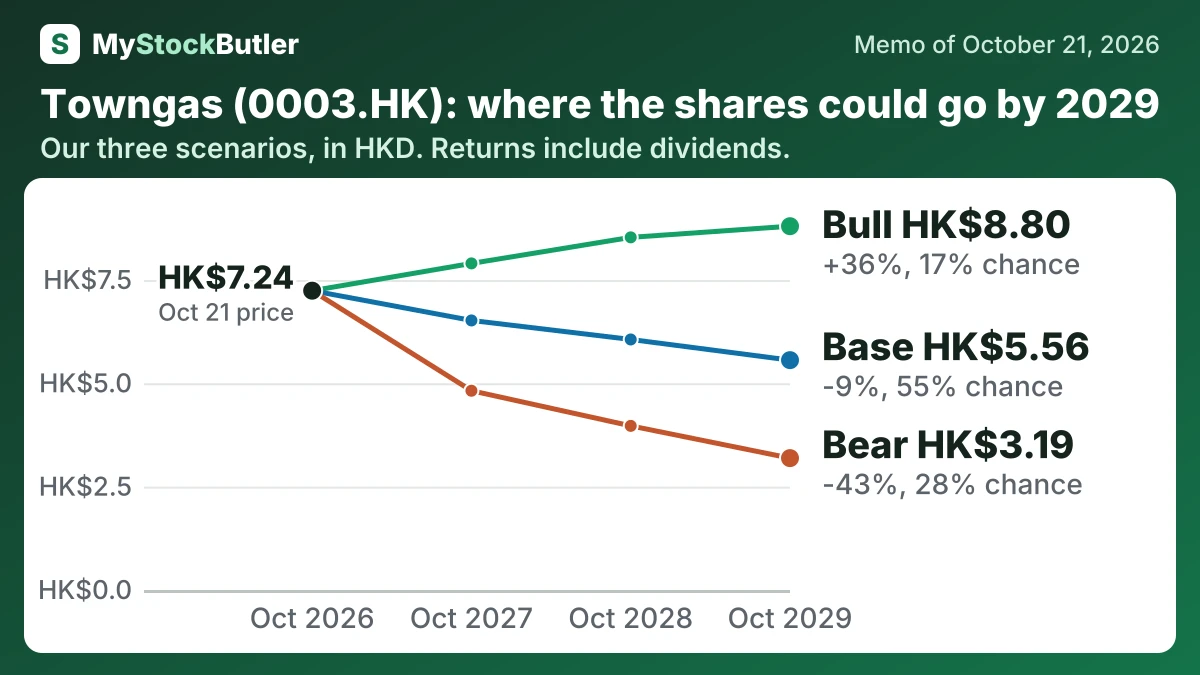
| Case | Probability | October 2027 | October 2028 | October 2029 |
|---|---|---|---|---|
| Bear | 28% | 4.82 (-28%) | 3.97 (-36%) | 3.19 (-43%) |
| Base | 55% | 6.52 (-5%) | 6.06 (-7%) | 5.56 (-9%) |
| Bull | 17% | 7.90 (+14%) | 8.53 (+28%) | 8.80 (+36%) |
| Weighted | 100% | 6.28 (-8%) | 5.90 (-9%) | 5.45 (-11%) |
What has to go right for Towngas, and what could go wrong?
The bear case starts at HK$6,000m. It falls 5% annually to HK$5,700m in 2028 and HK$5,415m in 2029. The bull case starts at HK$6,700m and grows 8% annually to HK$7,236m in 2028 and HK$7,815m in 2029. The bear case reflects weak demand, tariff limits and poor newer-business returns; the bull case requires stable margins, stronger volumes and successful EcoCeres execution. Mainland volume was nearly flat despite customer growth, while the company missed both Hong Kong and mainland gas-volume guidance in all four checked years.
The base case assumes the 2026 plan broadly holds: modest mainland growth, a RMB0.55/m³ margin and stable Hong Kong utility earnings. Its 55% probability reflects stable recurring earnings outside the disposal gain, but also the pressure from investment, refinancing and dividends.
How much cash does Towngas really make?
In 2025, Towngas generated HK$10,533.0 million from operations. Capital spending was HK$5,096.3 million, leaving free cash flow of HK$3,339.4 million after lease and interest payments. Deducting HK$63.9 million of stock pay produced “real free cash flow,” which treats employee share awards as an economic cost to owners.
| 2025 | 2024 | 2023 | 2022 | 2021 | |
|---|---|---|---|---|---|
| Cash from operations | 10,533.0 | 9,000.3 | 10,931.7 | 9,644.7 | 10,469.5 |
| − Capital spending | 5,096.3 | 6,435.5 | 8,359.7 | 7,724.7 | 7,273.5 |
| − Interest paid | 1,954.8 | 2,292.9 | 2,088.1 | 1,741.4 | 1,754.5 |
| = Free cash flow | 3,339.4 | 51.6 | -35.1 | 27.2 | 1,286.4 |
| − Stock pay | 63.9 | 0.0 | 48.9 | -13.5 | 36.5 |
| = Real free cash flow | 3,275.5 | 51.6 | -84.0 | 40.7 | 1,249.9 |
What this means. The table's free cash flow also subtracts lease payments and interest, even though its definition says it subtracts only spending on equipment.
What does an investor pay today for Towngas?
The price-to-earnings ratio, or P/E, tells investors how much they pay for each dollar of profit. The next-year P/E is only slightly lower than the trailing P/E, so the market is assuming little near-term earnings growth. That matters only if the profit is repeatable: gas-supply earnings deserve different treatment from gains created by selling an asset or revaluing property.
| Today (Oct 21, 2026) | |
|---|---|
| Share price | 7.235 |
| P/E, last 12 months (calculated) | 21.3x |
| P/E, next 12 months (calculated) | 21.1x |
| Free cash flow yield (calculated) | 2.5% |
| Real free cash flow yield (calculated) | 2.4% |
| Dividend yield (calculated) | 4.8% |
What this means. Enterprise value is higher than market value because it includes the company's debt and subtracts its cash, showing a broader price for the whole business.